Can't play sound? The illustrated version is right below.
The full narration of the video.
You owe money in several places at once. Your stomach knots up, and you don't know which one to pay first. Take a breath. Today we'll do just one thing: put them in order. Picture three things going wrong at home at once. A fire, a leak, a dead light bulb. You put out the fire first.
Debts work the same way. Don't just pay whoever yells the loudest. Ask of each one: what happens if I don't pay? Tier one: the ones that stop your life or your shop if they're cut off. Rent, power and water, wages, taxes. Tier two: the ones that go on your credit record and keep growing. Bank loans, credit cards, online loans.
In China, a bad mark like that stays on your record for five years after the debt is settled. Tier three: the ones you can talk through. Suppliers, family, friends. Last tier: the ones that can wait. What if one tier holds several debts? There are two ways to choose.
One: pay the highest interest first. You pay the least extra overall. That's the avalanche method. Two: pay the smallest balance first. One fewer person chasing you, fastest. That's the snowball method. One study followed nearly six thousand people paying off debt. The number of debts they cleared predicted who finished better than the amount they paid.
Clearing them one by one keeps you going. For debts with no interest, both ways cost the same, so pick the snowball. Next, take a sheet of paper and draw thirteen boxes. One box per week, about three months. In each box, write what comes in and what goes out that week. You can see right now which week will fall short.
For that short week, go talk to the people you owe, ahead of time. Don't hide. When you talk, give a specific date and amount. Pay part of it first. Once you agree, write it down. Finally, hold two lines. First: never take on costlier new debt to pay off old debt that charges no interest.
Second: debt takes up room in your head. Studies found that when people worry about money, their thinking gets stretched thin. So put the debts on one sheet and look at it once a week. The rest of the time, your mind is free for living. You don't have to pay it all at once. You only need to know which one comes next.
A fire, a leak and a dead bulb, all at once at home: you put out the fire first.
Debts work the same way. Ask of each one: what happens if I don't pay?
Don't just pay whoever yells the loudest. The U.S. Consumer Financial Protection Bureau (the government office that looks after people who borrow) gives the same advice to people who can't cover every bill: protect your home and your income first, then sort the rest.
Rent first, then the card, then talk to your friend. The biggest balance doesn't automatically go first.
Research says: the snowball is easier to stick with.
One study followed nearly 6,000 people paying off debt: how many debts they had fully cleared predicted who finished better than how much money they had paid. In another set of experiments, people who put their money on one debt at a time paid off about 15% faster than people who spread it evenly.
For debts with no interest (like a loan from a friend), the order doesn't change what you pay. So pick the snowball.
Either way: keep up the minimum on every debt so none goes late. Put whatever is left on one debt at a time.
One box per week, thirteen boxes, about three months.
Thirteen weeks is short enough to guess well and long enough to fix things. Plenty of companies run their cash on this same sheet: each week that ends, they add one more at the far end, so they always see three months ahead.
For the short week, go to the people you owe ahead of time. Don't wait for them to come to you.
The CFPB's advice: if you can't make a payment, call the person or company you owe and explain why. A money educator at the University of Illinois puts it more bluntly: if you don't ask, the answer is no.
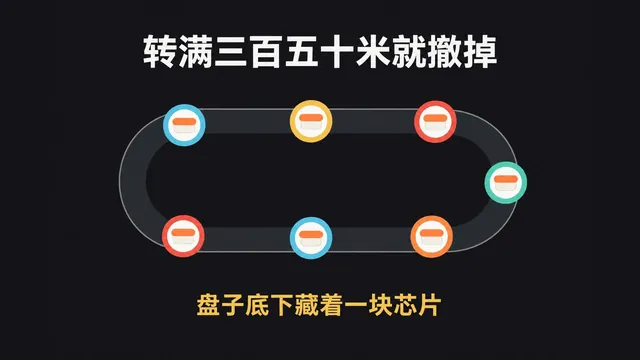
Why does sushi on a belt stay fresh? Every Sushiro plate carries a tiny chip that tracks how far it has travelled; after about 350 metres it comes off, and the same data tells the kitchen what to make.
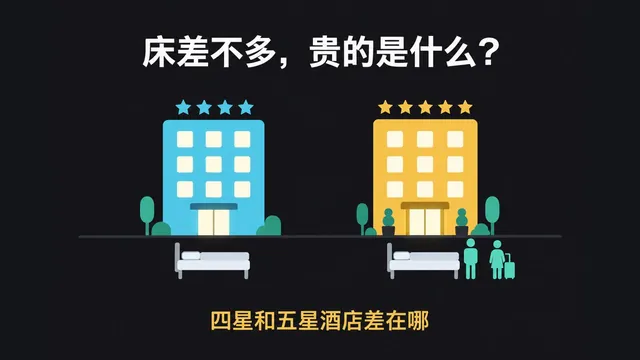
The rooms and beds can be nearly the same. The extra star mostly buys people: staff who are always there and think ahead for you.
Jim Rohn's 1981 ten-minute talk: your income can't outgrow you, plus three things you can start on today.
The marshmallow test was overturned: kids who eat it aren't weak-willed, they just don't trust promises. How two worlds grow apart, and what changes things.